
Not Just Another Index.
It’s The New Generation.®
We offer specialized solutions for investors seeking exposure to New Listings - a proxy for economic growth and innovation.

Upcoming Global IPOs
Transwarp (Ticker: 6727 HK) is a Chinese enterprise software company providing AI and big data infrastructure to corporate and government customers. Its software helps organizations store, manage and analyze large amounts of data, build AI applications and run cloud-based data systems. The company serves more than 1,800 customers across industries including finance, government, energy, healthcare, transportation and manufacturing, and says repeat purchases from existing customers accounted for more than 70% of revenue on average from 2023 through the first quarter of 2026.
Transwarp plans to list on the Hong Kong Stock Exchange on September 21, 2026, with an IPO raising approximately $88 million and an estimated market capitalization of about $948 million. According to Frost & Sullivan, Transwarp was China’s fifth-largest AI infrastructure software provider by revenue in 2025, with a 2.7% market share, and the country’s largest independent provider in the sector.
The company is also expanding internationally, with subsidiaries in Hong Kong, Singapore and Canada and customers in Singapore and the Middle East. BOCOM International, CMB International and several other securities firms are managing the offering.
Ligent Technologies Inc. (Ticker: 9856 HK) is a Chinese semiconductor and optical communications company that develops products used in high-speed data networks, including optical transceivers, chips and network terminals. Its technology is designed in part for AI-driven computing networks, where large amounts of data need to move quickly between servers and data centers. The company serves customers globally.
Ligent plans to list on the Hong Kong Stock Exchange on September 22, 2026. The company is offering approximately 172.01 million new shares at HKD 32.96 per share, raising about HKD 5.67 billion, or approximately $723 million. The offering implies a market capitalization of around $4.1 billion.
All shares in the IPO are primary shares, meaning the proceeds will go to Ligent rather than existing shareholders. The offering also includes a 15% greenshoe option. CLSA, Citigroup Global Markets Asia, Futu Securities International and GF Securities Hong Kong Brokerage are among the managers of the IPO.
Bamboo Insurance Services (Ticker: BMB US) is a U.S. homeowners insurance business that uses technology and AI to help price policies, assess risk and manage claims. The company operates as a managing general underwriter (MGU), meaning it handles much of the insurance process while partner insurance carriers provide the capital and ultimately bear the claims risk.
Bamboo, which is incorporated in Delaware and backed by CVC, plans to list on the New York Stock Exchange on September 23, 2026. Selling shareholders are offering 35 million shares at $18.00 to $20.00 each, implying proceeds of approximately $665 million at the midpoint and up to $700 million at the top of the range. The offering implies an estimated market capitalization of around $3.0 billion, while Reuters reported a fully diluted valuation of up to approximately $3.2 billion.
All shares in the IPO are being sold by existing shareholders, so Bamboo itself will not receive any proceeds from the offering. J.P. Morgan, Morgan Stanley, Deutsche Bank Securities, Evercore ISI and Wells Fargo Securities are managing the IPO.
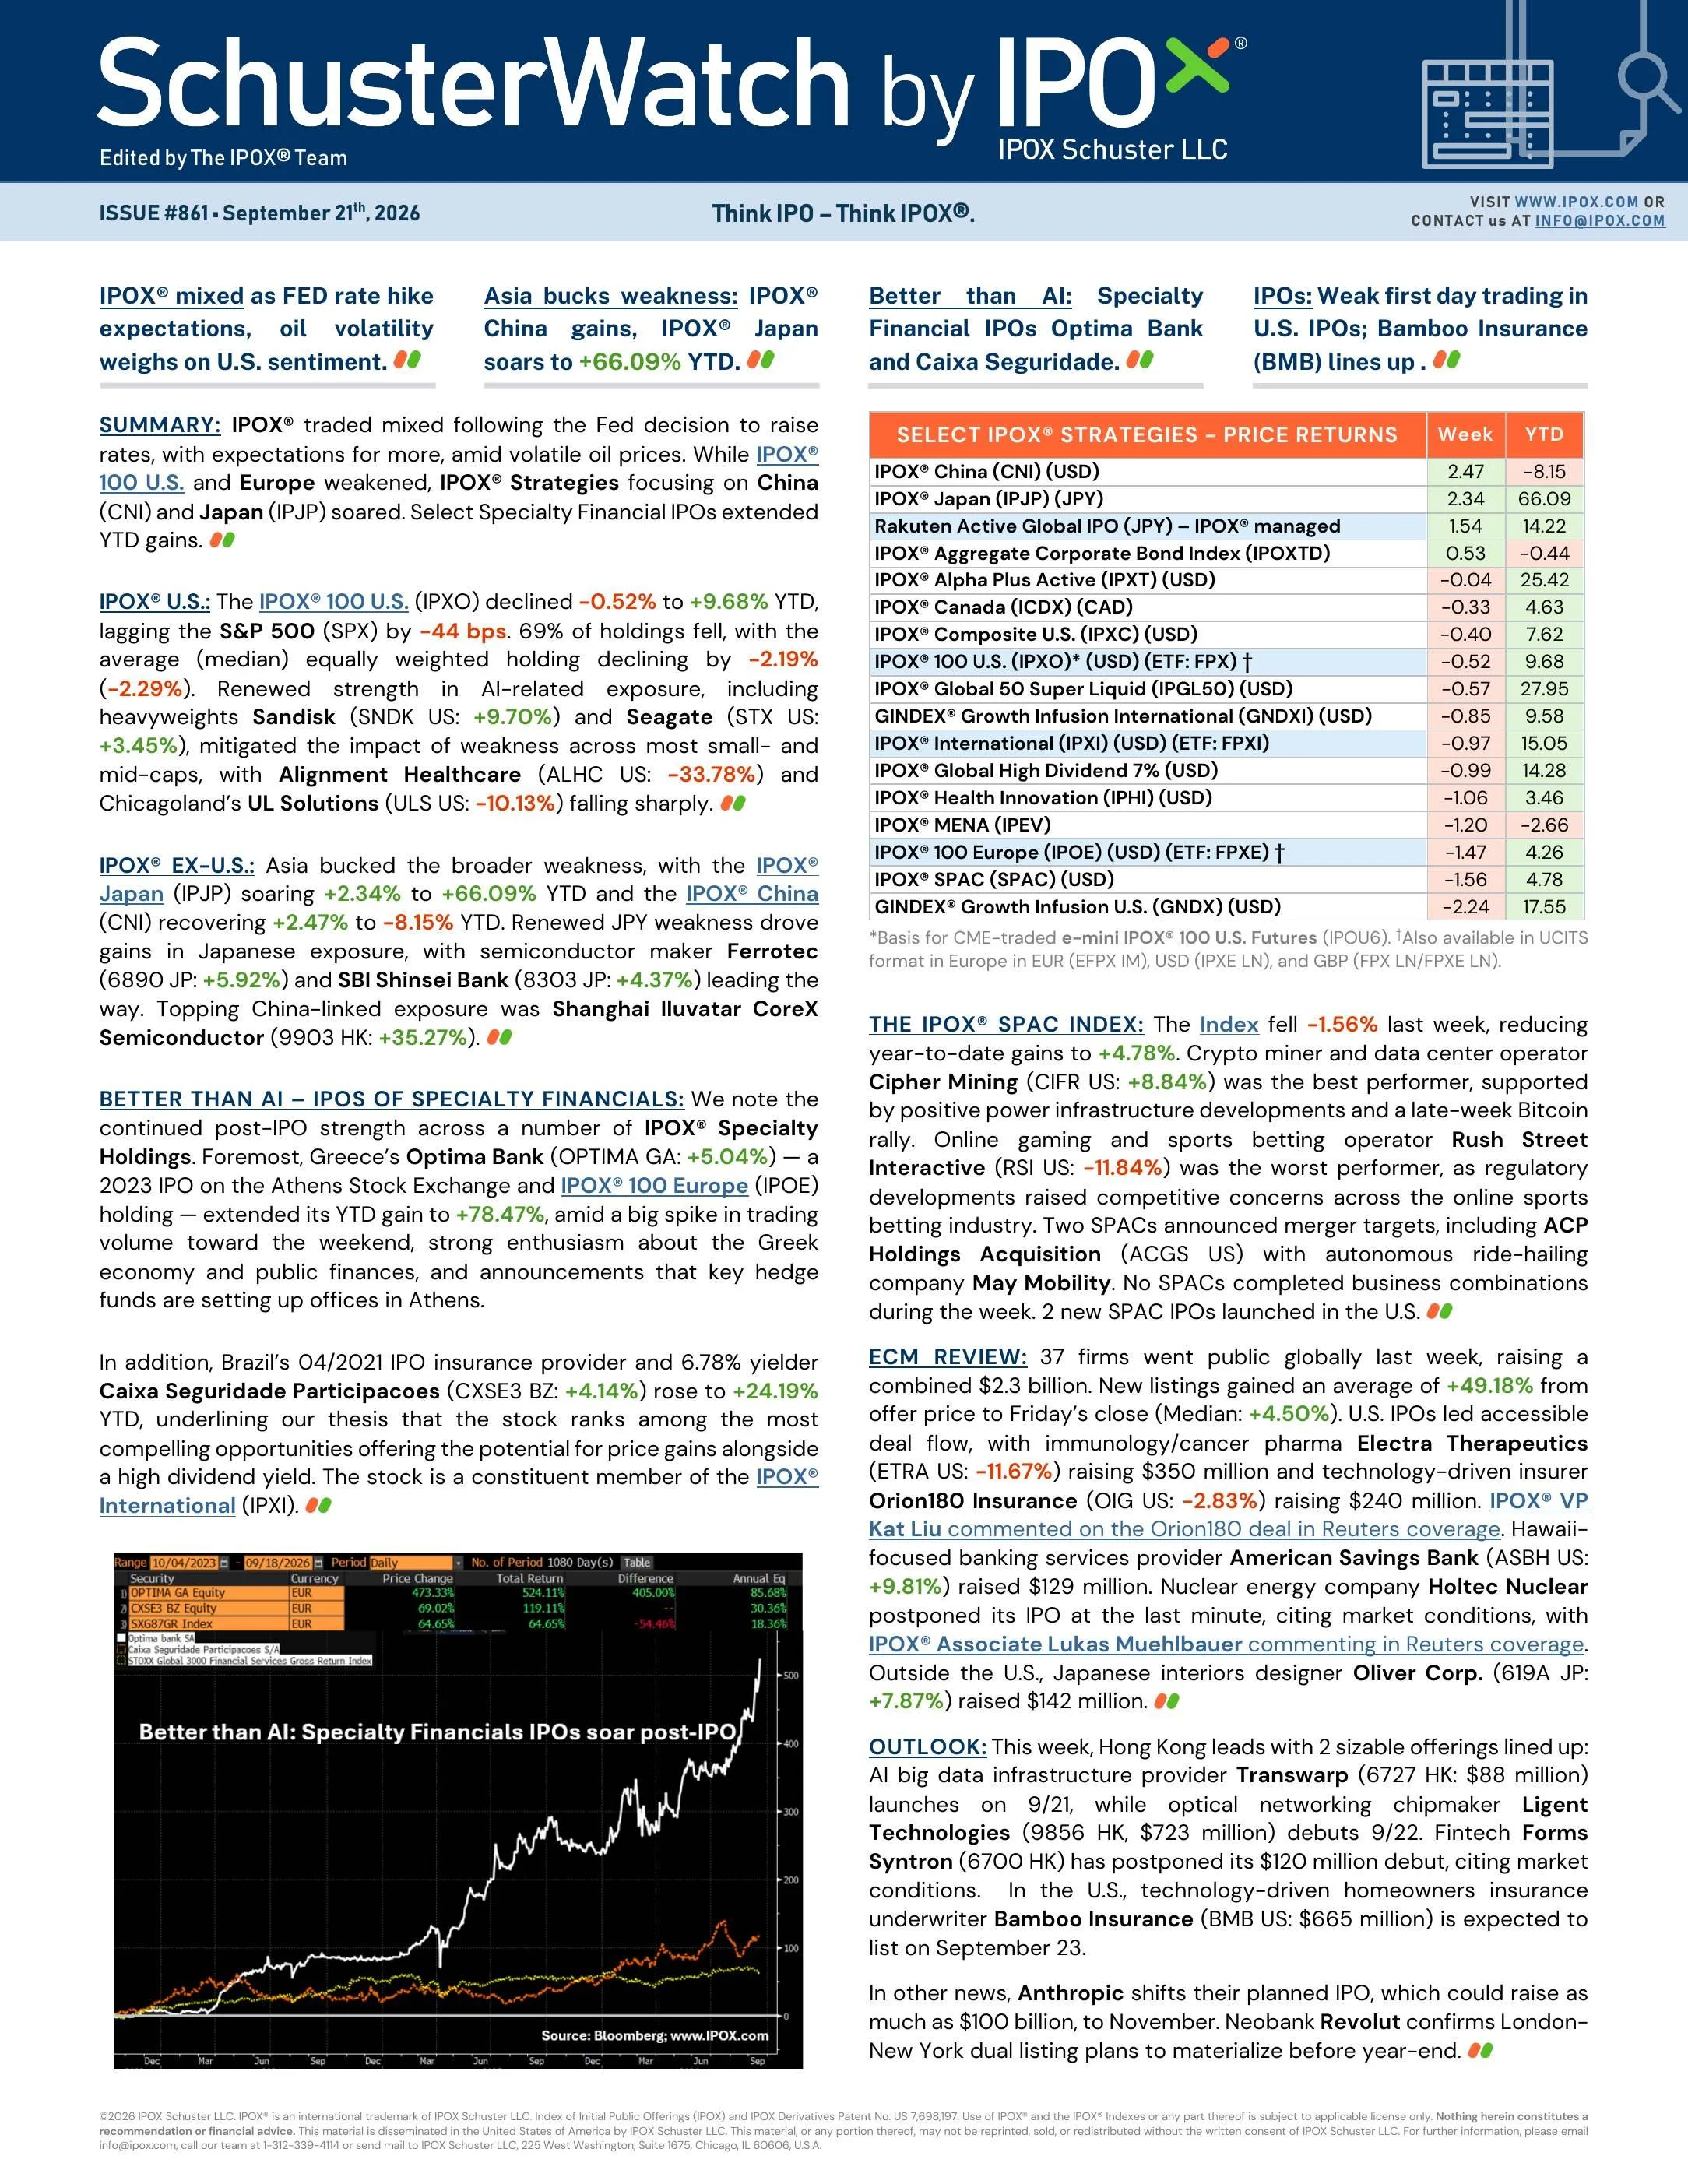


The IPOX® Newsletters
IPOX® in the News

IPOX® VP Kat Liu commented in Reuters on Orion180 Insurance’s Nasdaq debut and the excess and surplus insurance market. Liu explained that E&S carriers serve risks many traditional insurers cannot or do not want to write on standard terms, with greater flexibility in pricing, coverage limits and policy design. She added that Orion180’s opportunity has been accelerated by a cyclical dislocation as larger insurers pull back, rather than depending solely on those market conditions for its growth in the sector.
Reuters cited IPOX® Associate Lukas Muehlbauer on Holtec’s suspended U.S. IPO, linking the company’s investment case to expectations for higher electricity demand from data centres amid the AI boom. Muehlbauer said the broader IPO pipeline should remain active without widespread postponements, while noting investor concerns around AI development, interest rates, and weak nuclear-sector performance. “The underlying demand for energy has not disappeared, but investors are becoming more selective about how much they are willing to pay today for future growth.”
IPOX® Associate Lukas Muehlbauer commented on Altera’s planned U.S. IPO, highlighting investor focus on the chipmaker’s exposure to hyperscalers and AI infrastructure demand. Reuters reported that Altera, backed by Silver Lake and Intel, has confidentially filed to go public and could raise more than $2 billion. Muehlbauer noted that whether hyperscalers remain a material part of Altera’s customer base will be an important consideration for investors once the company’s public filing becomes available.
IPOX® VP Kat Liu said in Reuters coverage that SPAC mergers can provide a more flexible route for defense and space companies with government contracts, strategic backing or clear growth pipelines that lack the revenue scale or predictability required for traditional IPOs. Reuters reports six defense and space-related companies have announced SPAC mergers in 2026, double the total in 2025, as investor appetite surges. The sector is also benefiting from rising government spending and strong demand for satellite, defense and aerospace technologies this year.
IPOX® VP Kat Liu said insurance companies’ recurring revenue and resilient demand are attractive in volatile markets as Reuters covered CVC-backed Bamboo Insurance’s planned U.S. IPO. Bamboo is targeting a valuation of up to $3.24 billion, with selling shareholders seeking as much as $700 million. Liu also noted that Bamboo’s managing general underwriter model creates dependence on insurance carriers and capacity providers. The company plans to list on the NYSE under the ticker “BMB” amid relatively strong insurance IPO performance.
The IPOX® Update

Global IPO activity this week featured several large planned offerings alongside notable delays. Firmus Technologies is seeking up to $5 billion in Australia, while Bamboo Insurance targets up to $700 million in New York. BASF advanced plans for a major Frankfurt listing, and Revolut and Vue explored future London-linked IPOs. Holtec, Dusk and Forms Syntron postponed or shelved offerings. Other deals included Linjemontage in Stockholm, Wiluna Mining in Australia and RoboTechnik’s $800 million Hong Kong secondary listing during the period.

Global IPO activity is accelerating into the fall, with major prospective listings spanning the U.S., Europe, Asia-Pacific and MENA. Altera leads the pipeline with a potential $2 billion-plus U.S. IPO, while Holtec Nuclear, Stratolaunch and Orion180 advance offerings. Europe features Belron and Ignis, while Asia-Pacific activity includes AirTrunk, Mynt, Musinsa and Transwarp Technology. In MENA, MNT-Halan has begun the Cairo listing process, highlighting broad investor appetite across technology, infrastructure, defense, insurance and fintech as issuance momentum builds toward year-end globally.

U.S. IPO activity is led by SB Energy’s planned $5 billion Nasdaq deal, alongside Cumberland Farms’ pre-IPO financing and Golden Pet Brands’ New York plans. In Europe, Nscale is raising $3.5 billion ahead of a potential flotation, while Blackstone prepares Hotel Investment Partners for a Spanish listing. Asia-Pacific remains especially active, with Moonshot AI, Asia OneHealthcare, Ligent, Club Med, Akulaku, Jollibee’s international unit and VinFast-linked GSM all advancing toward Hong Kong or Malaysian IPOs across technology, healthcare, hospitality and mobility.