SchusterWatch #865 (10/12/2026)
IPOX® 100 U.S. (IPXO) well-supported as small caps near correction territory.
M&A, S&P 500 Inclusion underlines IPXO's role as a target market for CA's.
Movers in Focus: RXO, BSP, MANE, ASTS, ENEV3 BZ, CXSE3 BZ.
IPOs: Airtel Money slips in London debut, U.S. biotech listings lead issuance.
SUMMARY: IPOX® traded well-supported into U.S. Indigenous Peoples’ Day week, with good auctions for long-dated sovereign debt helping to stabilize yields, while U.S. small caps neared correction territory and the IPOX® SPAC (SPAC) entered a bear market.
IPOX® U.S.: The IPOX® 100 U.S. (IPXO) added +0.03% to +10.25% YTD, as voracious momentum continued to push the S&P 500 (SPX) towards its all-time high. Ahead of earnings, 55% of portfolio holdings rose, with the average (median) equally weighted stock adding +0.48% (+0.15%), outperforming the applied market-cap-weighted IPOX® 100 (IPXO). It was a big week for corporate actions (CAs), as 1) media firm Skydance (SKYD US: -3.58%) closed its deal to acquire IPOX® heavyweight Warner Brothers (WBD US), 2) infrastructure software maker Twilio (TWLO US: -1.73%) was added to the S&P 500 (SPX), and 3) trucking firm C.H. Robinson Worldwide (CHRW US: -9.77%) acquired innovative logistics services provider RXO (RXO US: +24.38%) at a significant premium, with RXO topping the list of best index performers for the second consecutive week. De-SPACs, typically on the outer edge of the risk spectrum, declined notably, with innovative communication services provider AST SpaceMobile (ASTS US: -12.81%) hit particularly hard as takeover hopes faded amid big declines in incumbent U.S. telecoms after IPOX® top holding SpaceX (SPCX US: +2.27%) bought wireless spectrum for its Starlink network.
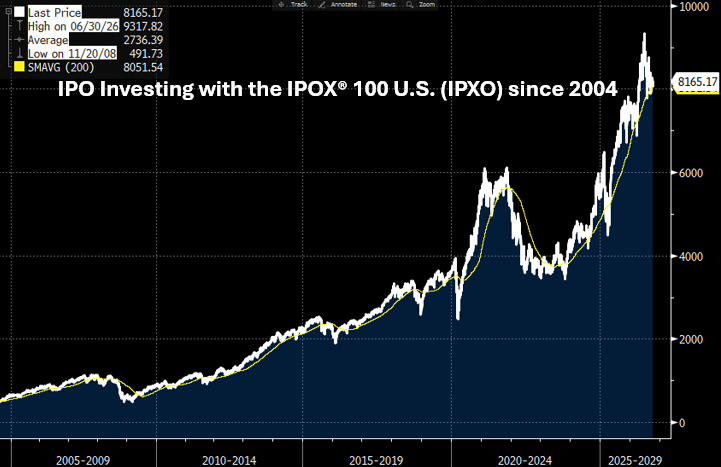
Figure: IPO Investing with the IPOX® 100 U.S. (ETF: FPX) since 08/2004

IPOX® EX-U.S.: Markets outside the U.S. traded mixed, with the IPOX® International (ETF: FPXI) declining to +14.63% YTD, lagging its benchmark by -6 bps, last week. Following elections, most of the upside was concentrated in our Brazilian portfolio holdings, with utility Eneva (ENEV3 BZ: +9.40%) and financial firm Caixa Seguridade (CXSE3 BZ: +2.25%), yielding 6.71% p.a., recording strong gains. Technology firms diverged sharply, including Japan’s semiconductor testing firm Advantest (6857 JP: +7.71%) as well as chipmakers Kioxia (285A JP: -9.30%), ARM (ARM US: -13.40%) and GigaDevice Semiconductor (3986 HK: -13.24%).
IPOX® SPAC INDEX: The Index fell sharply by -3.01% last week, pushing year-to-date performance into negative territory at -0.75%. Digital banking platform Dave (DAVE US: +6.30%) continued to be the best performer, supported by analyst price target increases. AI infrastructure developer SharonAI (SHAZ US: -23.35%) was the worst performer amid a broader selloff in AI-related stocks, with its small market capitalization potentially amplifying the decline despite no material company-specific catalyst. Five SPACs announced merger targets, including GigCapital8 (GIW US) with quantum computing company Quantisimo. No SPACs completed business combinations during the week. One new SPAC IPO launched in the U.S. market.
ECM REVIEW: 41 firms went public last week, raising a combined $2.4 billion. New listings gained an average of +18.18% from offer price to Friday’s close (Median: -0.65%). London led deal flow, with mobile money payments provider Airtel Money (AMC LN: -5.99%) raising $700 million in the city's biggest IPO since 2021. Shares traded lower during conditional trading, with regular public trading expected to begin Wednesday. Norway saw Singaporean tanker operator Volare (VLCC NO: +5.19%, $501 million), chip designer ESWIN Computing (1256 HK: -0.65%, $320 million) debuted in Hong Kong, and anti-drone defense firm Sensofusion (SENSO FH: +10.30%, $313 million) listed in Finland. U.S. Biotechs remained active, with inflammation pharma TRex Bio (TRXB US: +0.00%, $117 million) finishing flat and hypertension-focused Retension Pharma (RTSN US: -12.25%, $45 million) falling below offer price.
OUTLOOK: This week, the IPO calendar focuses on two sizable offerings: Hong Kong is set to welcome emerging-market smartphone producer Transsion (2636 HK, $409 million), targeting a $5.8 billion valuation. In the U.S., AI-powered cancer drug developer Iambic Therapeutics (IAM US, $150 million) is lined up at a valuation of $758 million. IPOX® VP Kat Liu was quoted by Reuters on the company's AI-driven drug discovery platform and valuation.