SchusterWatch #861 (09/21/2026)
IPOX® mixed as FED rate hike expectations, oil volatility weighs on U.S. sentiment.
Asia bucks weakness: IPOX® China gains, IPOX® Japan soars to +66.09% YTD.
Better than AI: Specialty Financial IPOs Optima Bank and Caixa Seguridade.
IPOs: Weak first day trading in U.S. IPOs; Bamboo Insurance (BMB) lines up .
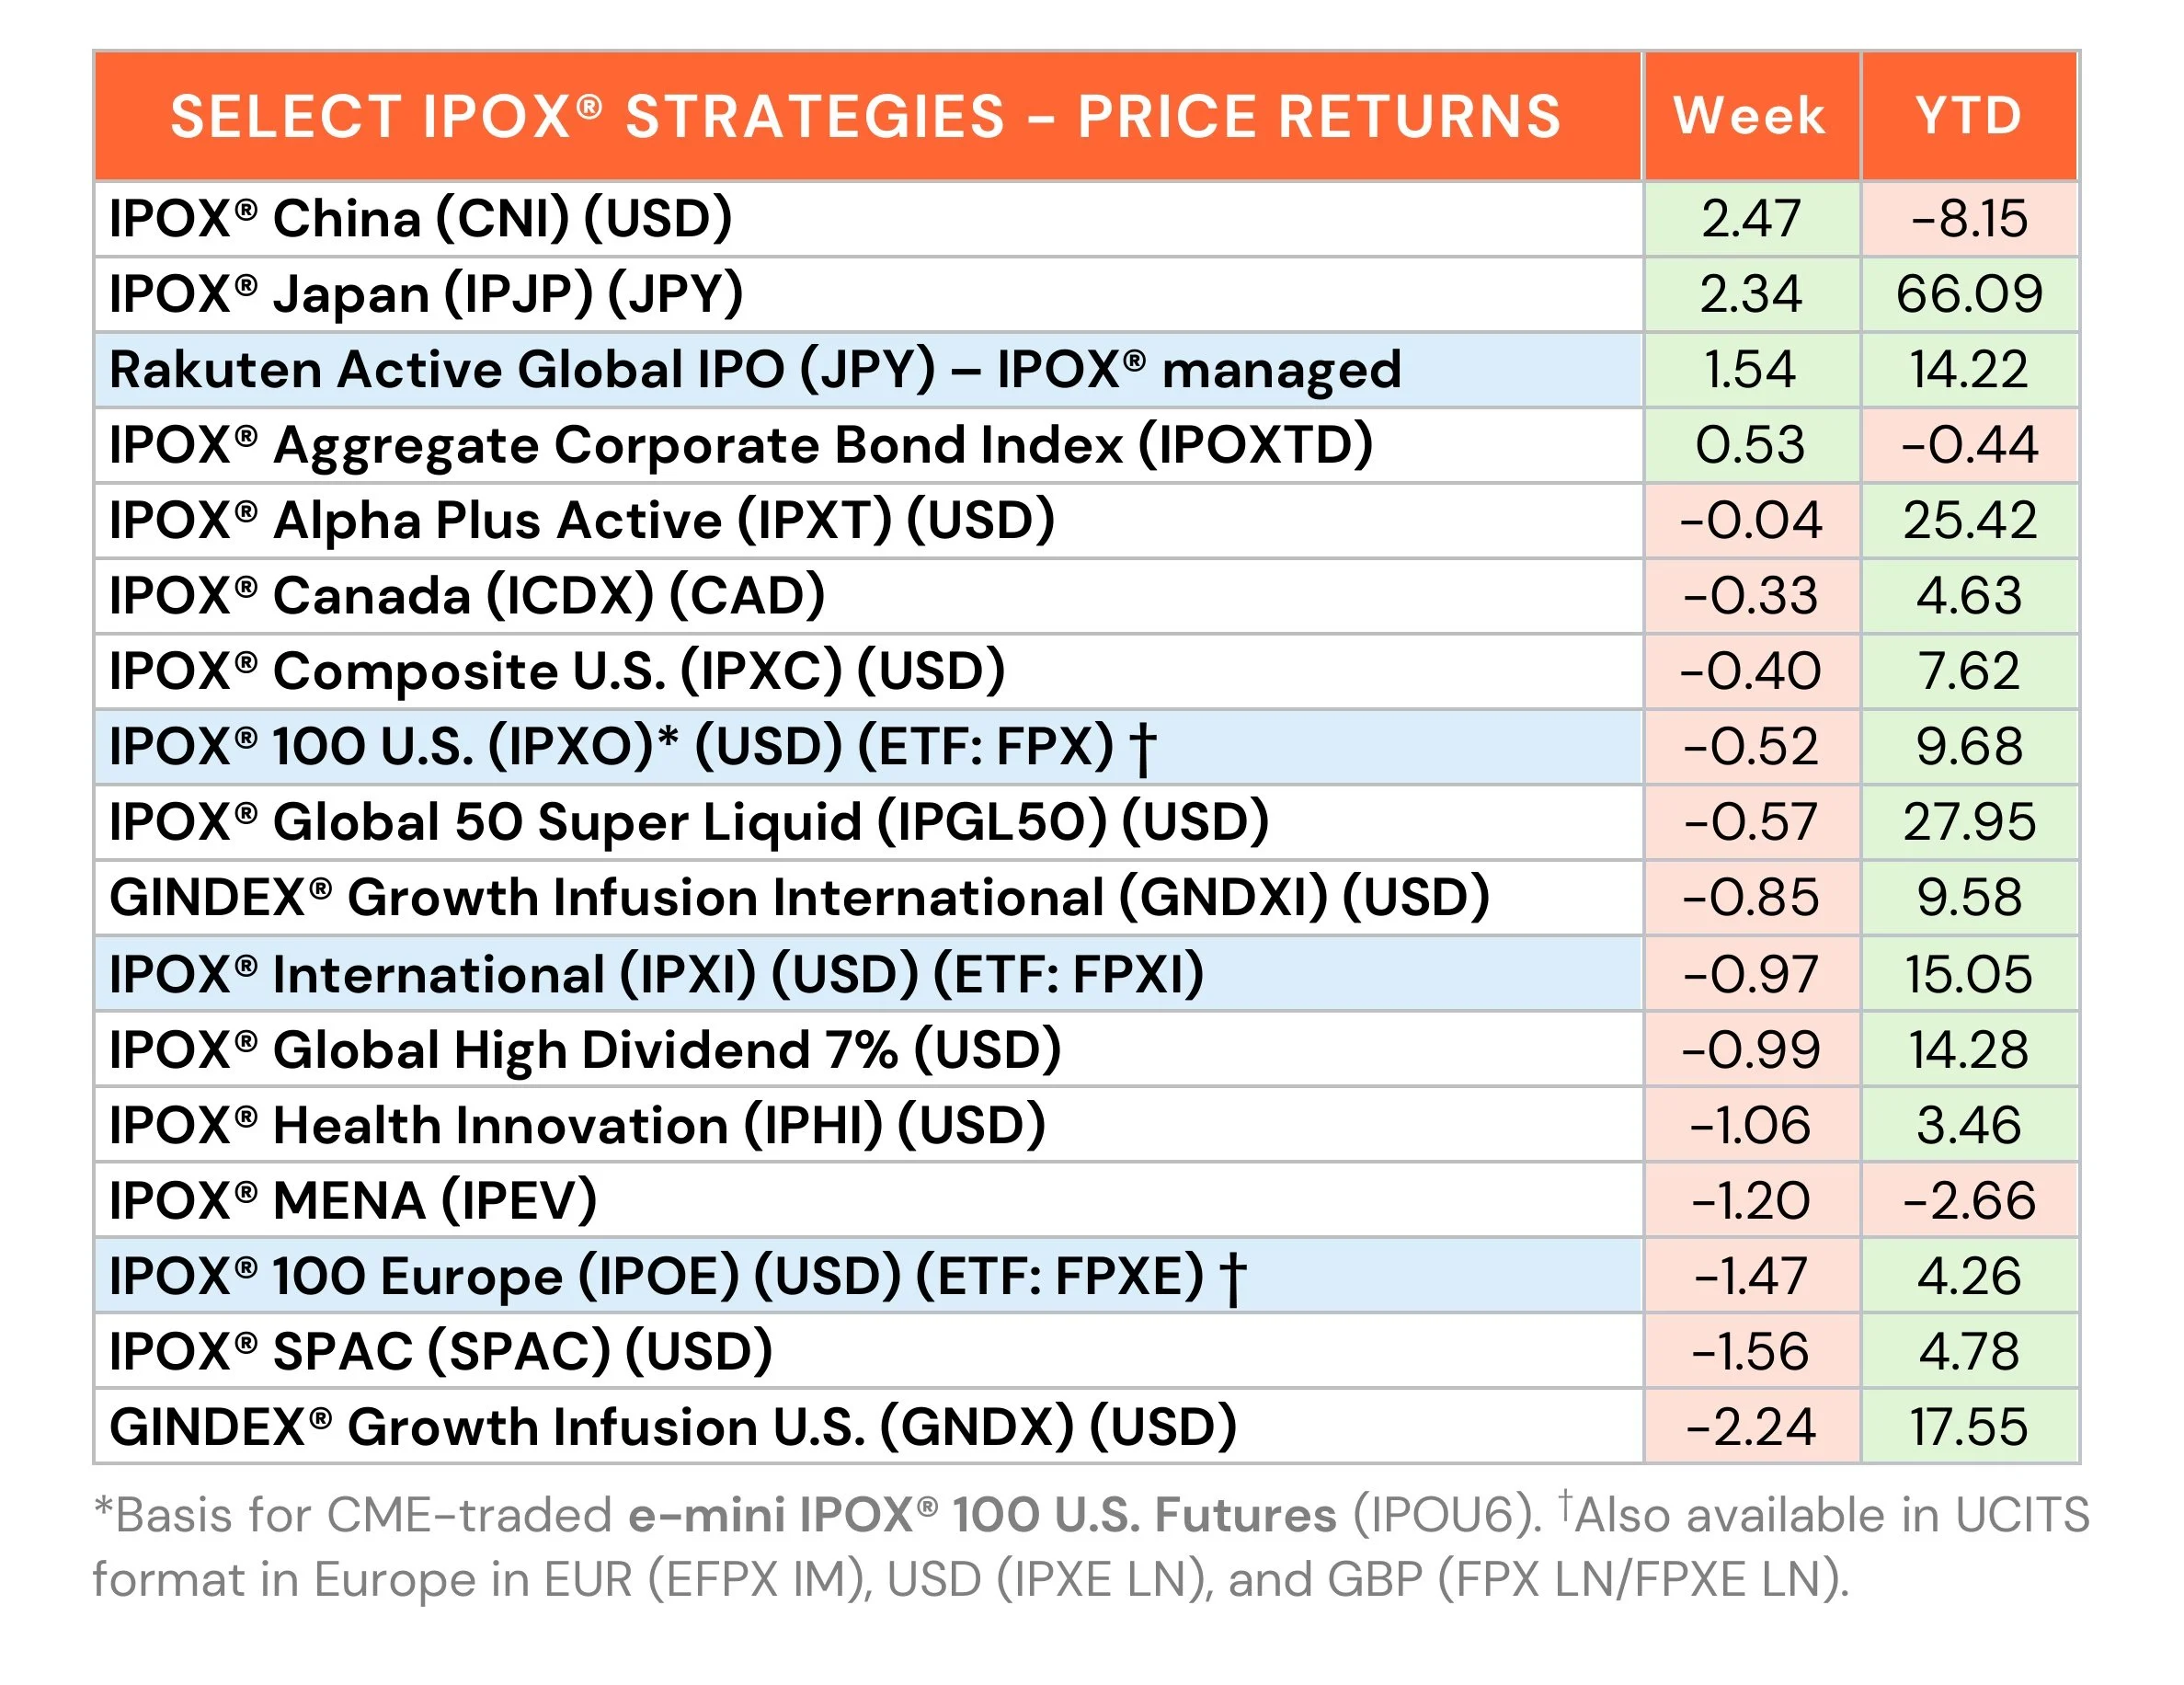
SUMMARY: IPOX® traded mixed following the Fed decision to raise rates, with expectations for more, amid volatile oil prices. While IPOX® 100 U.S. and Europe weakened, IPOX® Strategies focusing on China (CNI) and Japan (IPJP) soared. Select Specialty Financial IPOs extended YTD gains.
IPOX® U.S.: The IPOX® 100 U.S. (IPXO) declined -0.52% to +9.68% YTD, lagging the S&P 500 (SPX) by -44 bps. 69% of holdings fell, with the average (median) equally weighted holding declining by -2.19% (-2.29%). Renewed strength in AI-related exposure, including heavyweights Sandisk (SNDK US: +9.70%) and Seagate (STX US: +3.45%), mitigated the impact of weakness across most small- and mid-caps, with Alignment Healthcare (ALHC US: -33.78%) and Chicagoland’s UL Solutions (ULS US: -10.13%) falling sharply.
IPOX® EX-U.S.: Asia bucked the broader weakness, with the IPOX® Japan (IPJP) soaring +2.34% to +66.09% YTD and the IPOX® China (CNI) recovering +2.47% to -8.15% YTD. Renewed JPY weakness drove gains in Japanese exposure, with semiconductor maker Ferrotec (6890 JP: +5.92%) and SBI Shinsei Bank (8303 JP: +4.37%) leading the way. Topping China-linked exposure was Shanghai Iluvatar CoreX Semiconductor (9903 HK: +35.27%).
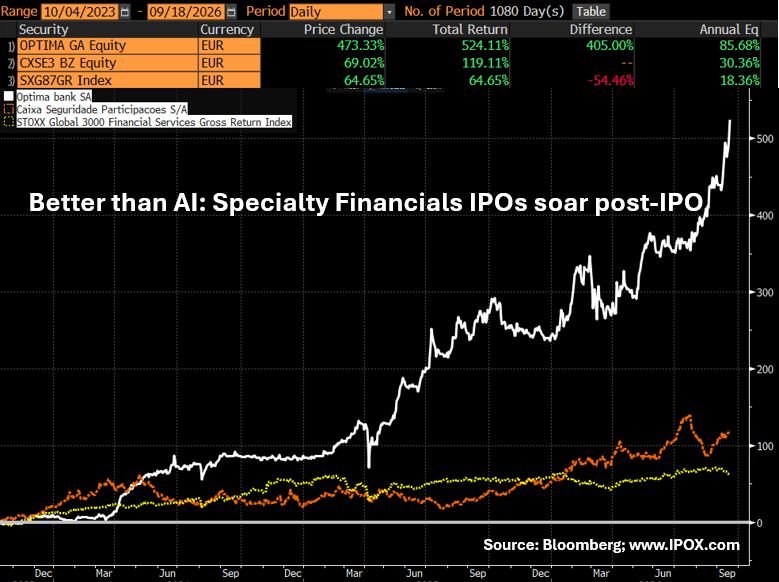
BETTER THAN AI – IPOS OF SPECIALTY FINANCIALS: We note the continued post-IPO strength across a number of IPOX® Specialty Holdings. Foremost, Greece’s Optima Bank (OPTIMA GA: +5.04%) — a 2023 IPO on the Athens Stock Exchange and IPOX® 100 Europe (IPOE) holding — extended its YTD gain to +78.47%, amid a big spike in trading volume toward the weekend, strong enthusiasm about the Greek economy and public finances, and announcements that key hedge funds are setting up offices in Athens.
In addition, Brazil’s 04/2021 IPO insurance provider and 6.78% yielder Caixa Seguridade Participacoes (CXSE3 BZ: +4.14%) rose to +24.19% YTD, underlining our thesis that the stock ranks among the most compelling opportunities offering the potential for price gains alongside a high dividend yield. The stock is a constituent member of the IPOX® International (IPXI).
THE IPOX® SPAC INDEX: The Index fell -1.56% last week, reducing year-to-date gains to +4.78%. Crypto miner and data center operator Cipher Mining (CIFR US: +8.84%) was the best performer, supported by positive power infrastructure developments and a late-week Bitcoin rally. Online gaming and sports betting operator Rush Street Interactive (RSI US: -11.84%) was the worst performer, as regulatory developments raised competitive concerns across the online sports betting industry. Two SPACs announced merger targets, including ACP Holdings Acquisition (ACGS US) with autonomous ride-hailing company May Mobility. No SPACs completed business combinations during the week. 2 new SPAC IPOs launched in the U.S.
ECM REVIEW: 37 firms went public globally last week, raising a combined $2.3 billion. New listings gained an average of +49.18% from offer price to Friday’s close (Median: +4.50%). U.S. IPOs led accessible deal flow, with immunology/cancer pharma Electra Therapeutics (ETRA US: -11.67%) raising $350 million and technology-driven insurer Orion180 Insurance (OIG US: -2.83%) raising $240 million. IPOX® VP Kat Liu commented on the Orion180 deal in Reuters coverage. Hawaii-focused banking services provider American Savings Bank (ASBH US: +9.81%) raised $129 million. Nuclear energy company Holtec Nuclear postponed its IPO at the last minute, citing market conditions, with IPOX® Associate Lukas Muehlbauer commenting in Reuters coverage. Outside the U.S., Japanese interiors designer Oliver Corp. (619A JP: +7.87%) raised $142 million.
OUTLOOK: This week, Hong Kong leads with 2 sizable offerings lined up: AI big data infrastructure provider Transwarp (6727 HK: $88 million) launches on 9/21, while optical networking chipmaker Ligent Technologies (9856 HK, $723 million) debuts 9/22. Fintech Forms Syntron (6700 HK) has postponed its $120 million debut, citing market conditions. In the U.S., technology-driven homeowners insurance underwriter Bamboo Insurance (BMB US: $665 million) is expected to list on September 23.
In other news, Anthropic shifts their planned IPO, which could raise as much as $100 billion, to November. Neobank Revolut confirms London-New York dual listing plans to materialize before year-end.