SchusterWatch #863 - Q3 2026 Review
Most IPOX® Spreads Fall Sharply as Sovereign Debt Yields Rocket in Q3.
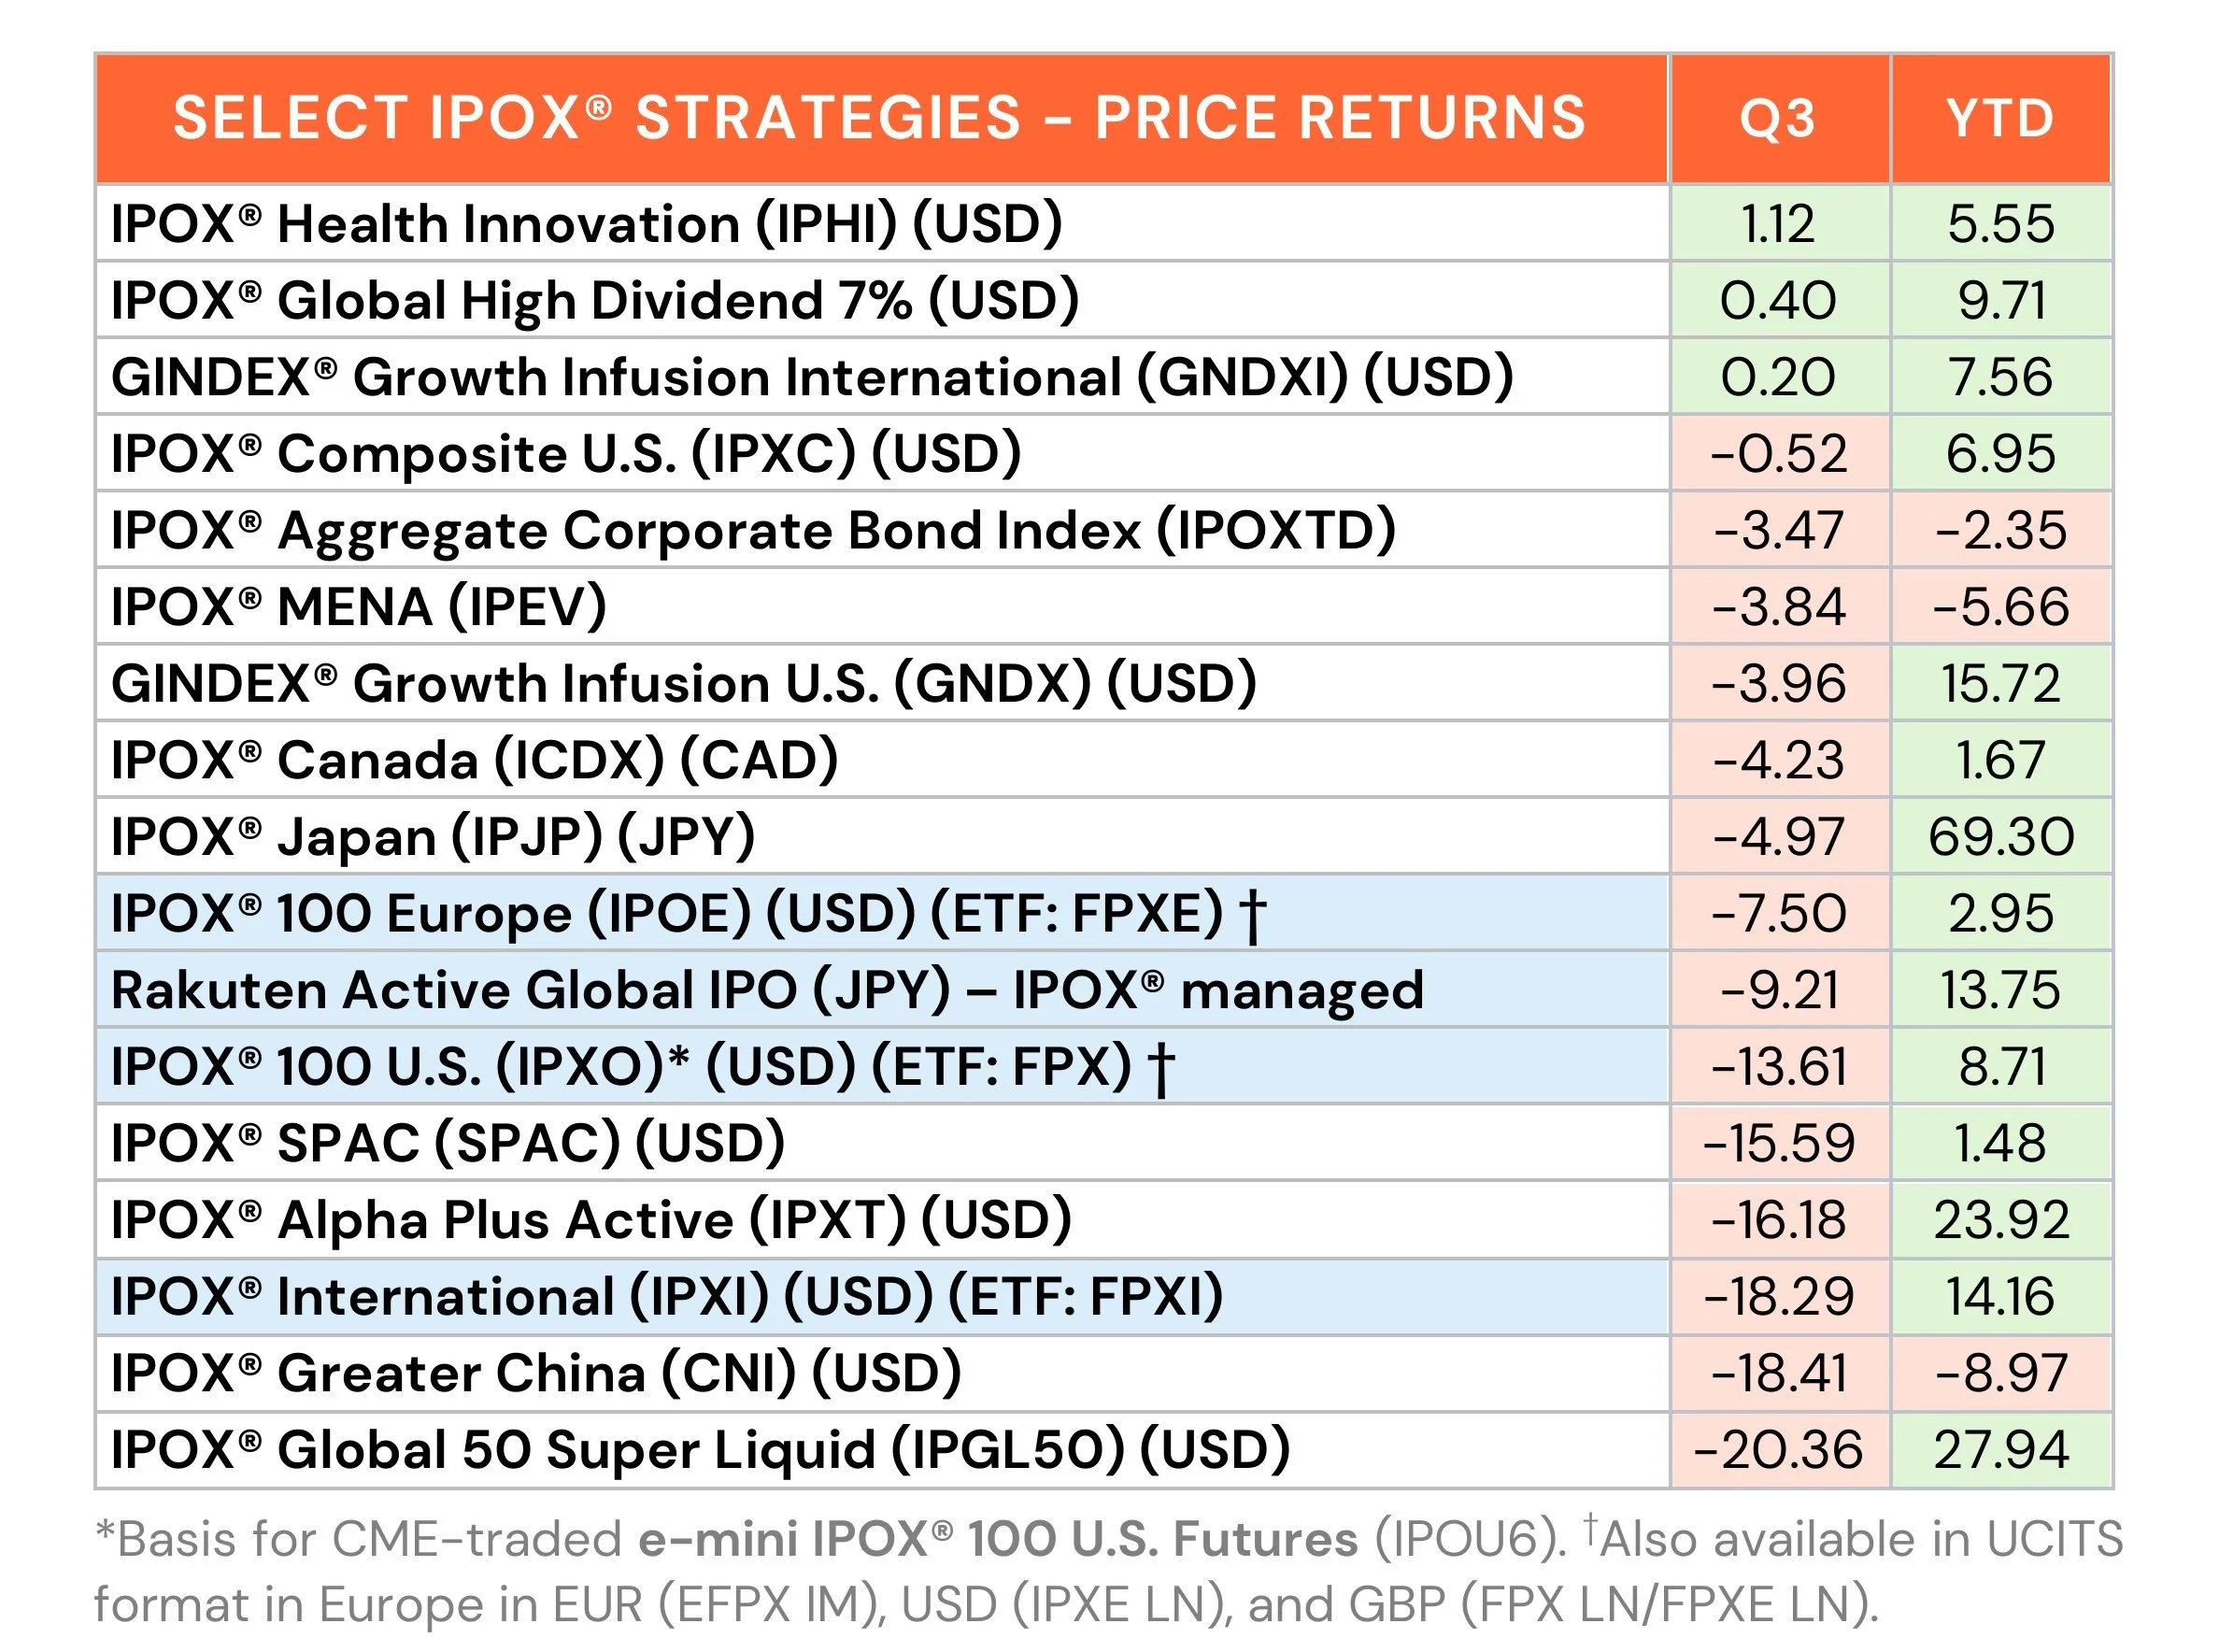
IPOX® 7% High Divi Leads: Adds +0.40% in Q3 to +9.71% YTD (ex. Divi).
Pockets of Strength focus on Specialty Financials and China Healthcare.
IPOs: Q3 Deal Flow Strong; AI-Focused U.S. Pipeline Builds for Q4.
SUMMARY: Most IPOX® Indexes fell sharply during Q3 2026, with spreads reversing some of the substantial three-year outperformance. We attribute much of the lacklustre showing to higher sovereign bond yields, with the U.S. 30-year yield now trading above 5.50% p.a., driving higher equity risk. Pockets of strength remained, while global IPO issuance sentiment soured.
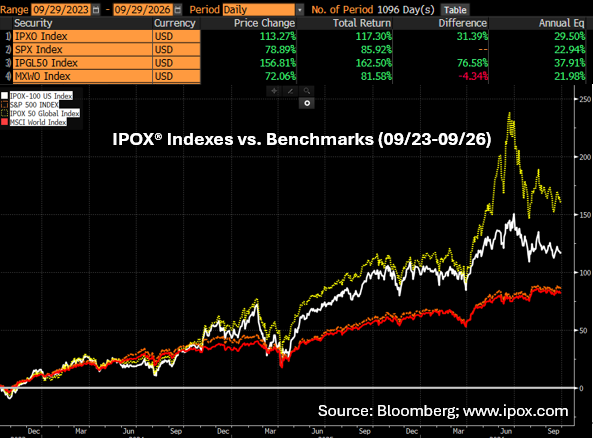
IPOX® U.S.: The IPOX® 100 U.S. (IPXO) fell -13.61% to +8.71% YTD during Q3, as higher rates and ongoing risk rotation drove significant profit-taking across many unseasoned stocks, while the main benchmarks played some catch-up after three years of relative underperformance. Among the weakest IPOX® portfolio holdings were building maintenance services firm 09/25 IPO Legence (LGN US: -37.02%), 10/25 spin-off chemicals producer Solstice (SOLS US: -36.35%) and certification provider 04/24 IPO UL Solutions (ULS US: -35.45%). Financial services provider 12/25 IPO Andersen Group (ANDG US: +44.22%) and initially hard-hit 03/26 IPO MiniMed (MMED US: +30.23%) were notable exceptions.
IPOX® EX U.S.: U.S. weakness extended across global regions, with the IPOX® Global China (CNI) dropping -18.41% to -8.97% YTD, while the IPOX® Japan (IPJP) shed just -4.97% to +69.30% YTD and the IPOX® 100 Europe (IPOE) weakened by -7.50% to +2.95% YTD. A pocket of market-adjusted strength emerged among Japanese and European financial services providers, led by regional banking group IPO M&A Hachijuni Nagano Bank (8359 JP: +21.46%), 12/25 IPO SBI Shinsei Bank (8303 JP: +13.89%) and 10/23 IPO corporate action candidate Greece-based banking group Optima Bank (OPTIMA GA: +47.80%). China-linked health biotechs also proved resilient, with a focus on 10/21 IPO CDMO provider Asymchem Laboratories (6821 HK: +56.62%), early-stage biotech 09/22 IPO Biocytogen (2315 HK: +49.76%) and later-stage 07/23 IPO SKB (6990 HK: +11.65%).
ECM REVIEW: 390 companies went public globally during Q3, raising a combined $96 billion. New listings gained an average of +39.77% from offer price through quarter-end (Median: +9.10%). U.S. exchanges hosted 29 offerings raising $36 billion, although the headline figure was heavily skewed by SK hynix (SKHY US: +23.59%), which raised $26.5 billion through a U.S. secondary listing alongside its long-established KOSPI listing (000660 KS).
U.S. activity was broad-based, Italian tech conglomerate and AOL-owner Bending Spoons (BSP US: +14.90%, $1.93 billion) and data-center operator Csquare (CSQR US: -24.71%, $1.21 billion) were among the largest technology deals, while sandwich chain Jersey Mike’s (JMKE US: -26.87%, $1.06 billion) led consumer issuance. AI infrastructure remained visible through data-center builder Accelevation (ACCV US: -0.28%, $540 million) and communications infrastructure provider ITG (ITG US: -51.41%, $359 million). Biopharma also delivered a notable cluster of sizable offerings, including ADARx Pharmaceuticals (ADRX US: +17.29%, $446 million), Braveheart Bio (BRVE US: +12.22%, $440 million), Latigo Biotherapeutics (LTGO US: -7.22%, $397 million) and Electra Therapeutics (ETRA US: -25.00%, $350 million), reflecting continued investor appetite for the sector amid positive aftermarket momentum across recent biotech issuance.
Hong Kong generated substantial deal flow, led by optical transceiver maker Zhongji Innolight (3308 HK: +8.37%, $7.83 billion), electronics manufacturer Luxshare Precision (2475 HK: -15.38%, $3.20 billion) and online fashion platform SHEIN (625 HK: -36.49%, $1.74 billion).
OUTLOOK: Q4 2026 could be dominated by several unusually large U.S. IPOs. Anthropic ($60+ billion potential), Switch (up to $10 billion), DayOne Data Centers ($5 billion), SB Energy (at least $5 billion) and Nscale ($3 billion) highlight a pipeline centered overwhelmingly on AI and the infrastructure required to support it. Hyperscale data centers, cloud-compute capacity, power generation and advanced AI platforms remain the dominant themes.
Investor demand continues to concentrate around businesses benefiting directly from accelerating AI capital expenditure, although execution should remain sensitive to valuation, market volatility and investors’ willingness to fund capital-intensive growth.